In This Article:
AVPT
Sponsored
The Illusion of Safety: Why AvePoint's AI Rally is a Dark Pool Distribution Trap
BearishStrongChange from report: +3.6%
Published on 2026-09-09 by TradeFomo
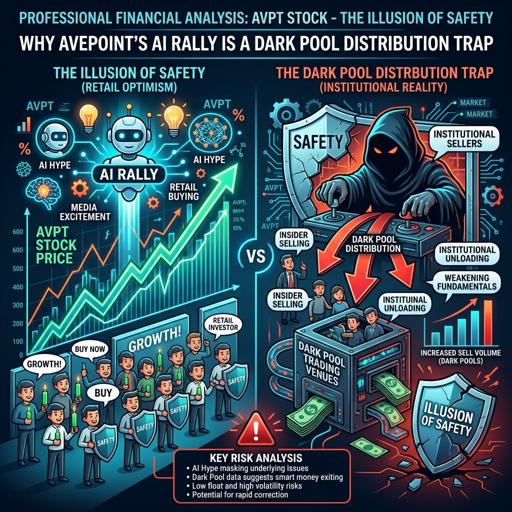
The Fundamental Façade and the Insider Exodus
On paper, AvePoint (AVPT) looks like a pristine technology darling perfectly positioned for the current era. The company’s Q2 2026 earnings report in early August was seemingly flawless: a 22% year-over-year revenue increase, total ARR surging to $465.1 million, and raised full-year guidance propelled by "strong demand for AI trust solutions." The market swallowed this narrative hook, line, and sinker, launching the stock from a June low of roughly $10.00 to a multi-month peak of $14.30 by late August.
But if the future is so unequivocally bright, why are the insiders rushing for the exits?
A closer look at SEC Form 4 filings paints a starkly contradictory picture. Throughout July and August, Chief Legal Officer Brian Michael Brown systematically dumped hundreds of thousands of dollars worth of shares. Most glaringly, on August 27—the exact day the stock printed its half-yearly high of $14.30—he liquidated 60,000 shares at $14.20. When the C-suite is aggressively unloading stock into a retail-driven AI euphoria, it is rarely a coincidence; it is a prelude to a harsh reality check.
Decoding the Dark Pools: The Anatomy of a Top
To truly understand the hidden mechanics behind AVPT's recent price action, we must analyze the synchronized behavior of the TRF ratio, OTC short percentage, volume Z-score, and rolling close position value. When viewed together, these four metrics peel back the curtain on institutional accumulation and distribution, revealing hidden long/short behaviors, abnormal fund flows, and volume-price divergences. A pivotal moment occurred on August 27th, precisely as AVPT reached its $14.30 peak. On this day, both the TRF ratio and the volume Z-score flashed simultaneous recent extremes—a classic quantitative signal that a prior trend is exhausting and a new, reversed trend is initiating. While retail participants were aggressively buying the breakout, institutions were utilizing off-exchange facilities to absorb the liquidity and offload risk. This was corroborated by the OTC short percentage spiking to the 93rd percentile, exposing massive hidden short selling in the dark pools at the absolute top. Since that structural inflection point, the rolling CLV has exhibited a steadily deteriorating trend. This degradation in rolling closing strength reflects a fundamental shift in the balance of power; intraday rallies are consistently being sold into, proving that the underlying multi-day momentum has transitioned from bullish conviction to bearish distribution.
Options Complacency: A Ticking Gamma Time Bomb
The options market confirms this precarious setup, revealing a dangerous level of complacency that borders on the absurd. Analyzing the extra time-series data, the Net DEX sits at a massive +5.68 million, highlighting that aggregate institutional exposure is overwhelmingly skewed to the long side, rendering the market highly vulnerable to a sudden unwind. Currently, the Net GEX remains positive (around +229k), meaning market makers are in a long gamma stance, which temporarily pins the price and forces mean reversion. However, the OTM put/call OI ratio has collapsed to an extreme low of 0.07 (a 0.0 percentile historical reading), indicating that tail-risk hedging has been completely abandoned by speculators blindly chasing the upside. Diving into the options snapshot, market pricing expectations are tightly bracketed by a front-month put wall at $13.00 (acting as key support) and a formidable macro call wall at $14.00, which has already proven to be a hard resistance ceiling. Furthermore, the expiration distribution shows that far-term gamma (October) dominates the near-term, while the term structure displays a staggering implied volatility premium for calls (22-63D call IV at 0.885 vs. put IV at 0.667). This extreme IV skew toward calls, combined with a total lack of downside OI protection, suggests that if the stock breaks below the crucial $13.00 put wall, Net GEX could rapidly flip negative. Such a transition would correspond to a violent price inflection point, igniting a severe structural sell-off as dealers are forced to sell the underlying to hedge their negative gamma exposure, amplifying the downward volatility.
The Contrarian Verdict
The crowd is currently treating AvePoint as a bulletproof AI governance play, but the market's plumbing tells a story of systemic, calculated distribution. The "smart money" is not buying the breakout; they are supplying the shares to retail. The golden cross and the overbought RSI readings from late July and August were the bait. Now, with a technical dead cross above zero printed on September 2nd, the price action is finally beginning to align with the dark pool reality.
When insiders are aggressively selling the exact top, dark pool shorting hits extremes on maximum volume, and the options market is priced for absolute perfection with zero downside protection, the risk/reward asymmetry violently shifts. AVPT is currently floating on the fumes of long-gamma mean reversion and retail complacency. But gravity in the markets is undefeated, and the trap has already been set.
Sponsored